AI | More Business Wisdom
Rice Business faculty are exploring big questions about AI and how it’s reshaping business, technology and the classroom.
To innovate overseas, learn from foreign businesses at home.
Based on research by Haiyang Li and Yan Anthea Zhang
To Innovate Overseas, Learn From Foreign Businesses At Home
For centuries, raw materials and technology flowed along the Silk Road between China and the West. Ideas, including Islam and Buddhism, math and medicine, traveled as well. And as global trade spread, innovation did too.
The same trends continue today. Or at least they do most of the time. According to Haiyang Li and Yan Anthea Zhang, management professors at Rice Business, international expansion in some cases actually dampens product innovation. It's not globalization that’s the problem, Li and Zhang say, but the splitting of a company’s resources between domestic and overseas markets, especially in emerging market firms.
Previous scholars, they argue, assumed that when such a company split resources, its share in the domestic market remained constant. But they found to the contrary: As a firm increases its international market share, its domestic market share decreases. And when the company’s domestic market dwindles, so too do the opportunities to search for novel ideas for that market.
To test their ideas, Li, Zhang and coauthor Jie Wu of the University of Macau looked at China, an emerging market whose firms tend to pursue aggressive internationalization to gain world-class technology and capability. Because China’s domestic market is growing rapidly at the same time, however, these companies can’t disregard it.
Li, Zhang and Wu studied 883 manufacturing firms in China. Analyzing data from the World Bank and Chinese National Bureau of Statistics, the scholars examined manufacturing firms from Beijing, Chengdu, Guangzhou, Shanghai and Tianjin. What they found is that firms that divided resources between domestic and international markets often were less innovative.
Because these companies serve both domestic and overseas markets, managers often ran short on time or resources to create novel ideas, and ended up imitating their peers. It’s a particularly thorny problem for emerging market firms, whose leaders are less likely to have global management experience. Aesop aside, necessity seems to squelch invention.
The more widely the Chinese firms expanded geographically, in fact, the less they innovated. There was just one scenario in which the Chinese firms’ innovation boomed along with global expansion: when businesses faced high import penetration on their home turf.
Companies that had to deal with such penetration, the researchers discovered, had seen diverse paths to doing business already in their own market. So they were better prepared to go international than companies in more provincial marketplaces. In other words, the Silk Road had already come to them.
Throughout history, world travel has been a path to new ideas — and prompted new ideas in the travelers themselves. Zhang, Li and Wu offer a provocative insight about the limits of this kind of movement. If a company doesn’t have the capacity to take advantage of its new horizons, its power to invent actually shrinks.
The best way for companies to build that capacity? Paradoxically, embrace the foreign presence at home.
Haiyang Li is a professor of strategic management
Yan Anthea Zhang is the Fayez Sarofim Vanguard Professor of Management in Strategic Management at the Jones Graduate School of Business at Rice University
To learn more, please see: Li, H., Zhang, Y. A., and Wu, J. (2012). The role of internationalization in the product innovation of emerging market firms. Academy of Management Annual Meeting Proceedings. (2012) p.1.
Rice Business faculty are exploring big questions about AI and how it’s reshaping business, technology and the classroom.
The only thing the market likes less than a late report? Silence.
Based on research by K. Ramesh, Tiago Duarte-Silva, Huijing Fu and Christopher F. Noe
It’s human nature, apparently, to read no news as bad news. Relaying something — anything — about the cause of a late report seems to soothe investors’ nerves by preventing them from filling the silence themselves.
Key findings:
Investors eagerly wait for the news in their earnings reports. When these reports don’t appear on the expected date, investors worry — and stock prices often fall as a result. But what if managers could present late reports in a way that spared their companies?
Research by K. Ramesh, a professor at Rice Business, shows that managers’ approach to late earnings reports can profoundly affect market reaction. When firms put off filing a report, it’s up to managers to decide whether to speak up or stay quiet. Those who choose to talk about a postponement then must decide how, what and how much to say.
All earnings delays, whether they’re attended by a statement or not, prompt negative market reaction, prior research suggests. But in his research, Ramesh, Herbert S. Autrey Professor of Accounting, wanted to learn more about the exact consequences of these late reports, and how managers can lessen the blowback.
To do this, Ramesh and a team of coauthors first looked at the incidence, timing and contents of a comprehensive sample of press releases announcing an earnings delay. Then they studied what those delays did to market value.
Conventional wisdom in the business press already suggested that investors viewed any announcement of a delayed earnings report as bad news. But finance theorists tell a more complicated story, one in which the market response might be partially shaped by managerial behavior. Subtle factors, they found, such as whether the impending delay is discussed or treated with silence, really can make a difference.
In the view of some theorists, merely announcing a delay can sometimes avert a drop in stock prices. Others argue that this isn’t necessarily the case, especially if the company discloses that the delay stemmed from legal concerns. The better approach: making it clear up front that reports aren't being postponed to hide disastrous information. But what if the information is indeed disastrous?
That may be the one case where disclosure won’t change much, Ramesh and his team found.
“Those companies that are in fact concealing disastrous results will experience no benefits (in the form of higher stock price) from revealing their true situation,” the research team wrote, “because the market will infer the worst from the manager’s decision not to announce the delay.” For this reason, they added, delayed earnings without a stated explanation prompt the most negative market reaction. As in so many areas of public relations, without a narrative, investors will infer a negative one of their own.
To better understand the impact of late reports, Ramesh and his coauthors built a comprehensive sample of 545 delay announcements by using a keyword search of the Dow Jones Factiva database between January 1, 1995, and December 31, 2009.
As conventional wisdom suggested, the study showed that announcements of late earnings reports led to negative market reactions. (Earlier studies have shown smaller firms are hit hardest by this dynamic, perhaps because investors assume large companies have more finely tuned financial reporting systems, so are less worried by their earnings delays).
Consistent with the anecdotal evidence, the average one-day abnormal stock return for the sample was -6.29 percent, while the median return was -2.27 percent. Both figures are economically and statistically significant.
The researchers next classified the announcements according to stated reason, dividing the delays into “Accounting” and “Non-Accounting” categories. “Accounting” explanations were subdivided into “Accounting Issue,” “Accounting Process” and “Rule Change.”
Meanwhile, “Non-Accounting” explanations were divided into “Business,” which linked the delay to some event such as divestitures or regulatory proceedings, and “Other,” which ranged from earthquakes to power outages. Finally, there were delays for no stated reason at all.
About two-thirds of the late announcements, the team found, were linked to accounting. When firms named a specific accounting issue as the cause for delay, the average abnormal return reached a statistically significant -8.15 percent. When managers explained that the accounting process was not complete, the average abnormal return was slightly lower, at -7.04 percent.
After accounting issues, business events drove most earnings delays. In theory, these events could have been either good or bad news. But the average abnormal return for the subsample was a statistically significant -3.74 percent — a reflection of the fact that most business events linked to late earnings reports tend to be negative.
Curiously, the average abnormal return for the grouping classified as “Other” was almost nil — at 0.53 percent. This suggests that the market does not penalize managers for events outside of their control that have little, if any, relevance to firm performance.
“No Reason,” the researchers found, was the most damaging explanation of all. Seven percent of the sample, or 37 out of 545 delays, came without a stated reason. The average abnormal return for these was a significant -10.41 percent, a greater negative number than the returns for any of the other reasons.
So what should managers do when a deadline is going to be busted? Bite the bullet and disclose the reasons, Ramesh suggests. For one thing, it helps limit legal exposure and preserve credibility. When the reason for the late report is innocuous, explaining to investors can also mitigate the market’s displeasure. A caveat: While informing investors that a power outage caused earnings delay will calm jitters, disclosure may not make a difference if the company just can’t balance its books.
It’s human nature, apparently, to read no news as bad news. Relaying something — anything — about the cause of a late report seems to soothe investors’ nerves by preventing them from filling the silence themselves.
Duarte-Silva, T., Fu, H., Noe, C., & Ramesh, K. (2013). “How do investors interpret announcements of earnings delays?” Journal of Applied Corporate Finance 25(1): 64-71.
Failing to win awards can drive CEOs to make risky decisions.
Based on research by Yan Anthea Zhang, Robert E. Hoskisson (George R. Brown Emeritus Professor of Management) and Wei Shi
Failing To Win Awards Can Drive CEOs To Risky Decisions
Everyone likes a prize. From gold stars for obedient children to national awards bestowed on business titans, research shows that positive reinforcement works. But what happens to those who don’t win?
A recent study by business school professor Yan Anthea Zhang and emeritus professor Robert E. Hoskisson, along with former Rice Business doctoral student and current professor at Indiana University, Wei Shi, concluded that awards competitions can actually harm companies when the CEO doesn’t win. And chances to lose are abundant: Media outlets such as Businessweek, Harvard Business Review and Forbes are just a few of the publications that run CEO competitions.
While the winners instantly earn celebrity status, the researchers found that the almost-winners yearn for what they did not get and chase public acclaim by making more and larger acquisitions. The effect on non-winning CEOs is even more pronounced if the competition is close.
To explain how this happens, the authors turn to social psychology. Behavioral influences, they argue, can lead to poor strategic decision-making. Social comparison theory, meanwhile, posits that humans instinctively judge our status relative to others with whom we identify. That’s not always bad. When individuals compare themselves to superior others, known as upward comparison, it can fuel the wish to improve.
But when the individuals are corporate leaders—by definition achievement-oriented and status-driven—the comparing can get out of hand. These leaders notice when someone else in their group wins acclaim.
So what is an overlooked CEO to do? The most straightforward option is to redirect resources to improving company performance. Financial results, after all, are at the heart of CEO competitions. But this approach takes time. Acquisitions, on the other hand, draw an instant spotlight. The bigger the firm, the greater the crowd of stakeholders—and more attention for the dealmaker. Acquisitions, in other words, are a fast track for a CEO who’s lost a competition and wants to save face.
The rise in acquisitions from a pre-award period to a post-award period shows the competitions’ effect. They were 8.2 percent higher than the rise in acquisitions for control groups. (The control groups were acquiring companies in industries that overlapped those of firms with competitor CEOs who didn’t win awards, but didn’t overlap those of firms whose CEOs were award winners). The value of those acquisitions after the awards period increased too: They were 70.9 percent higher than that seen among control firms.
That’s not to say the acquisitions were good choices. The scholars compared the value of firms in the days before, during and after an acquisition was announced, and on average, companies that lost an award saw a drop in the value of acquisitions they made after the competition period, compared to the value of acquisitions they made in the pre-award period.
What’s more, if the rivalry was really intense—especially if the CEOs knew each other—the negative effects of these acquisition decisions were worse.
To test this dynamic, the three professors used S&P 500 companies in ExecuComp, which supplies pay and demographic data on top managers, for the years 1996 through 2010. The sample group excluded firms headquartered outside the U.S. and only considered awards given out by major U.S. publications. After winner CEOs were identified, the researchers identified their close competitors: CEOs leading companies of a similar size and with a similar product portfolio. In most cases, they looked at acquisitions made during the periods four years before an award was given, and compared that to the four years after.
Board members, managers and shareholders may all want to take note. Spotting the negative effects of awards is crucial, since as in so much of life losers far outnumber the winners.
Nor are all awards are created equally. Failing to win the prestigious award from Businessweek (the magazine with the highest circulation) had a particularly triggering effect, prompting more CEOs’ acquisition activity than other awards.
While that’s little more than human nature in action, shareholders naturally expect a bit more than that to guide firm decisions. A simple question might help. Faced with a CEO proposing an acquisition, perhaps the board should ask first, “When was the last time you didn’t win an award?”
Yan Anthea Zhang is the Fayez Sarofim Vanguard Professor of Management in Strategic Management
Robert E. Hoskisson is the George R. Brown Emeritus Professor of Management at Jones Graduate School of Business at Rice University
To learn more, see: Shi, W., Zhang, Y. A., & Hoskisson, R. E. (2017). Ripple effects of CEO awards: Investigating the acquisition activities of superstar CEOs’ competitors. Strategic Management Journal, 38(10), 2080-2102.
In peer-to-peer lending, appearances can tell the truth
Based on research Jefferson Duarte, Stephan Siegel and Lance Young
In Peer-to-Peer Lending, Appearances Can Tell The Truth
View the cartoon based on this article here: Lie Detector
Don’t judge a book by its cover, goes the saying. After all, beauty is only skin deep. And appearances can be deceiving. But according to research led by Rice Business professor Jefferson Duarte and coauthors Stephan Siegel and Lance Young, in some financial transactions, where there's smoke there's actually fire. In peer-to-peer lending, the researchers found, borrowers who look more trustworthy to lenders—based on photos alone—have better loan success. Not only that: They have higher credit scores and lower default rates.
Psychologists have understood for some time that people form impressions based on appearance, and that for better or worse those impressions affect social outcomes. Taller men are often perceived to be more adept leaders, for example. Conversely, recent Rice research shows that overweight men are treated less well in retail environments than men who weigh less. Economics and finance researchers, meanwhile, have focused on how perceived attractiveness relates to both pay and assumptions of competence.
Duarte’s research is unique, however, because it focuses on how appearance-based judgments affect perceptions of trustworthiness—and whether those perceptions in turn shape lending decisions.
The research team was interested in appearance-based judgments of trustworthiness because trust is so pivotal in financial transactions. To find out how appearance guided financial decisions, they decided to analyze data from a peer-to-peer lending site. On the site, a potential borrower posts a request for a three-year unsecured fixed rate loan. Her request, called a listing, includes the amount she wants to borrow and the top interest rate she is willing to pay. The site then conducts online auctions in which individual lenders bid on the potential borrower’s request. If enough lenders submit bids, the listing becomes a funded loan.
Because borrowers could upload photographs with their applications, Duarte and his team were able to analyze the role of appearance in this process. Their sample consisted of 5,950 loans, including 3,291 with photographs. First, the team asked 25 people to rate potential borrowers based on photographs alone. To determine the appearance of trust, they asked the raters to rank the trustworthiness of the person in the foreground of each photo on a scale of 1 to 5.
Interestingly, there was no consistency in the images that the potential borrowers posted of themselves. The photos include pictures of the borrowers in uniform, posing with their pets and drinking beer with friends.
Next, the researchers asked raters, "Assuming they have the money to pay you back, what are the chances that they would, in fact, pay you back?” For each question and photograph the team averaged the responses to get a consensus of a borrower's perceived trustworthiness and perceived willingness to pay.
Perhaps unsurprisingly, a “trustworthy” appearance clearly swayed lenders' decisions. Candidates with an aura of trustworthiness were more successful at getting a fully funded loan and better interest rates. In fact, borrowers in the top fifth quintile of perceived trustworthiness were offered interest rates 50 basis points lower than borrowers who appeared less trustworthy.
Far more surprising: Borrowers who looked trustworthy also turned out to have better credit grades and a lower probability of loan default. Appearance of trustworthiness, in short, accurately matched the borrowers' character.
The team theorized several explanations for these findings. Though appearance is often a misleading predictor of actual personality traits, it can accurately predict certain behaviors, such as risk taking and aggression.
Perhaps a person’s appearance, some subtle mix of grooming, facial expression and musculature, eventually comes to reflect his or her reputation. Perhaps a trustworthy appearance and trustworthiness itself both have a common biological origin.
The implications are profound for lenders, aspiring borrowers—and future researchers, including ethicists. Is it possible, for example, to identify the specific components that make someone look "trustworthy"? Which of these is voluntary, such as color of clothing, natural versus synthetic fibers, orthodontia and authentic-looking smiles? And which are the result of life experience, nutrition, even genetics, such as smoker’s teeth, a wide-open smile or elusive gaze? What precisely is the interaction between appearance, treatment by others and behavior?
In short, when it comes to lending, you really can judge a book by its cover. But volumes remain unknown about how and why.
Jefferson Duarte is a Gerald D. Hines Associate Professor of Real Estate Finance at Jones Graduate School of Business at Rice University.
To learn more, please see: Duarte, J., Siegel, S., & Young, L. (2012). Trust and credit: The role of appearance in peer-to-peer lending. Review of Financial Studies, 25, 2455-2484.
U.S. consumers and businesses are now facing a future of more expensive borrowing.
How employees shape the companies that help reshape society.
Based on research Scott Sonenshein
How Employees Shape The Companies That Help Reshape Society
Once only whispered about at the water cooler, the cause of equal rights for the LGBT community has become a shout loud enough to be heard in the executive suite.
The rise in volume is striking. Ten years ago, many mainstream workplaces ignored or actively dismissed the experiences of gay workers. Compare that to 2016, when North Carolina proposed a bill that many saw as biased, and firms including Dow Chemical, Hewlett Packard and PepsiCo used their financial clout to fight it. State-sanctioned discrimination against the LGBT community, they argued, would drive the nation’s most talented job candidates from North Carolina.
Did the CEOs come out swinging against prejudice simply because they felt it was the right thing to do? Probably not. Instead, their own employees increasingly made their values known, and swayed their leaders to act. What’s less clear is how they did it. While corporate leaders can direct company resources to promote and protect their causes, employees must be more resourceful to get their point across.
Scott Sonenshein, a management professor at Rice Business, examined some of their strategies in a recent study of language and power in the workplace. Rather than meekly adopting the views of their managers, Sonenshein found, employees consciously harness specific tools to change executives’ understanding of issues — while still preserving the firm’s core values.
Their main tool: “selling” their causes by framing them in work-friendly terms.
Sonenshein’s model lets researchers track an idea to see how its language and meaning shift as employees tailor it to resonate with decision-makers. Take the example of a human resources manager who passionately believes her company should recruit a diverse workforce because it would redress past discrimination. By the time she presents her idea to superiors, the HR chief likely will offer a different argument: that hiring a diverse staff will create access to a broader range of customers and potentially boost sales.
By “embellishing” some aspects of the issue and “subtracting” others, the manager has reframed — or, as Sonenshein puts it, “crafted” — the issue to gain better traction. In fact, even when an individual strongly believes a cause simply is “the right thing to do,” he or she still uses economic embellishment to push the idea through the ranks, Sonenshein found.
Sonenshein’s model also shows how power affects the crafting process. When an individual worker engages in issue-crafting, Sonenshein found, it’s usually in response to explicit company values. So in a company that prizes the bottom line above all else, workplace activists make a point to give justifications that support the company’s economic goals.
This effort is especially pronounced when advocates attempt to sell their idea upward in the ranks. Conversely, the crafting effort drops relative to the employee’s clout at work. In other words, the more power workers have in an organization, the smaller the discrepancy between what they believe about an issue and how they talk about it in public.
There’s plenty more research to be done, Sonenshein notes, especially about how crafting social issues at work affects individuals and the organizations themselves. What Sonenshein’s model offers is a framework for pursuing those questions — and insight into the way individual choices, language and status are shaping the firms that are reshaping society.
Scott Sonenshein is the Henry Gardiner Symonds Professor of Management at Jones Graduate School of Business at Rice University. He is the author of “Stretch: Unlock the Power of Less — and Achieve More Than You Ever Imagined.”
To learn more, please see: Sonenshein, S. (2006). Crafting social issues at work. Academy of Management Journal, 49(6), 1158-1172.

If department stores are to survive, they have to recapture a time when they were destinations in themselves.
By Mary Lee Grant
If American Department Stores Are To Survive, They Have To Become Destinations In Themselves Again
Lucy Kruse loved the smell of perfume enveloping her as she entered the department stores of her youth. She remembers trying on soft leather gloves, and following a splash of color to the store’s elaborate hats with their feathers and veils. At Sakowitz in Houston, she peered into the Sky Terrace restaurant to see fashion models sashay past the tables.
From the Christmas windows of Marshall Field’s in Chicago to the extravagance of Neiman Marcus in Dallas, department stores once defined the modern retail experience. Created to be emporiums of pleasure, however, today they are falling off the map.
This month, Macy’s announced the closing 100 of stores nationwide and layoffs for about 10,000 workers. The closings include three stores in Houston: Greenspoint Mall, Pasadena Town Square and West Oaks Mall.
During the same month, Sears announced that it will close 150 stores by April—10 percent of its locations. The company shuttered 78 stores last year and more than 200 in 2015. JCPenney, meanwhile, has announced it will be closing branches too.
The cause, most experts say, is online shopping. “The short answer is Amazon.com,” said Harold Livesay, a professor of business history at Texas A&M University and author of Andrew Carnegie and the Rise of Big Business. “The long answer is FedEx, UPS and the Internet. The infrastructure is reliable and so is the ease of delivery. You can shop from home, and don’t have to schlep to the store.”
There’s no doubt that e-commerce plays a substantial role in the demise of department stores. But customers may not be abandoning department stores just because they want to shop in their pajamas from the couch. Yet there may be more to the story. Paradoxically, while department stores are failing in the U.S., in China many are thriving.
According to recent research, about a third of China’s urban dwellers shop at department stores more than once a week.
“Department stores in China are suffering from online competition too, but they are doing better than in America because they have a different kind of concept of what a department store is,” said Haiyang Li, professor of strategic management at Rice Business in Houston. “They have added different entertainment elements, like ice skating rinks and cinemas and children’s playgrounds and restaurants. Shopping is more experiential in China. It is not just grab something and go.”
Department stores in the U.S. once offered this sense of excitement. Even small towns boasted department stores that were destinations. When Kruse, now 94, was growing up in Kingsville, she found it thrilling to take the area’s only escalator up to the tea room for lunch at Ragland’s.
But Kruse doesn’t shop much at department stores anymore, even though she is healthy and fit. Instead, she shops online or orders out of catalogues.
“Department stores used to be more elegant, and the staff was well-versed about the products,” she said. “The clerks really aren’t very helpful anymore. Shopping has become a chore and there is almost too much to choose from.”
In contrast, the Beijing-based Shimao department store recently reduced its retail floor space from 80 to 20 percent and added restaurants and entertainment areas. In Hong Kong’s Crawford Lane, concierges assist customers on every floor and 60 personal stylists stand ready to help shoppers craft their own individual chic looks. And in Shanghai, when the upscale French department store Printemps opened a branch it included a five-story high-speed slide in the shape of a dragon so shoppers could swish from the top floor to the bottom.
The Chinese stores hark back to a time when service, extravagance and play characterized European and American department stores. The department store became the epitome of elegance and luxury in the late 19th century, as entrepreneurs invented a new style of consumption in which shopping equaled pleasure. French author Emile Zola set his novel Au Bonheur des Dames (The Ladies’ Delight) in the Paris department store Le Bon Marche. As the owner enticed his female customers into purchasing an exotic array of appealingly arranged goods, the dramatic customs of this new institution unfolded among the staff.
In the United States, from the 1890s into the 1960s, American department stores hired the best architects to design their flagships on prime downtown real estate. Each store’s restaurant boasted a signature dish, from deviled crab to chicken velvet soup. Filene’s offered a health menu, from which weary shoppers could refresh themselves with potassium broth, acidophilus milk or a cold glass of kraut juice.
These stores played a central role in a city’s identity, too. Their tall clocks were meeting places where memories began. Any child born in Georgia received a birthday card from Rich’s. In Dallas, the Neiman-Marcus offered its famous his and hers gift at Christmas, with offerings ranging from airplanes to mummies to live camels. In Chicago, Marshall Field’s was such an institution that after the bombing of Pearl Harbor, one woman reportedly exclaimed, “Nothing is left anymore, except, thank God, Marshall Field’s.”
Chinese department stores, where shopping tends to be a group activity, today play a similar communal role, Li said. The stores offer a stage for the new middle and upper class to parade their status and a familiar hub where family and friends to reconnect. They’re even associated with romance. Chinese branches of IKEA have become such popular places for Chinese in their 70s and 80s to go on dates that IKEA has made new rules limiting the length of their stays.
“My thought is there is differentiation in China,” Li said. “People go online for some kinds of things, but they also want to go shopping so they can enjoy the unique environment the stores create. In the United States, there is no need to go to Macy’s. You don’t add any value by going there.”
At least for now, Chinese retailers seem to think both shopping styles can coexist. The same week Macy’s and Sears announced their closures, Chinese online retail giant Alibaba revealed that it would become the controlling shareholder of the Chinese department store and mall company, Intime, and would begin integrating its enormous e-commerce assets with Intime’s brick and mortar stores. Rather than foreseeing competition with physical stores, Alibaba plans to tap the latest technology to draw customers to stores, including artificial intelligence, virtual reality and Internet-of-Things.
If department stores in the West are to survive, they may have to somehow recapture a time when they were destinations in themselves—a time when women like Lucy Kruse were excited to ride the escalator and savor lunch in luxurious surroundings. They may have to revive the art of customer service. And they will have to figure out how to blend the convenience of technology with the real-life scent of perfume and the warmth of crowds.
This article originally appeared online in Gray Matters.
Mary Lee Grant has a degree in history from Yale University and a PhD from Texas A&M University, specializing in Mexican-American history and gender history.
Scott Sonenshein teaches us we all have more to work with than we can imagine.
By Scott Sonenshein
An Excerpt From Stretch A Book By Rice Business Professor Scott Sonenshein
Copyright © 2017 by Scott Sonenshein. Reprinted courtesy of HarperBusiness, an imprint of HarperCollins Publishers.
In the fall of 1961, a headstrong teenager named Dick left rural Pennsylvania to attend a military high school 150 miles away. Its rigid schedule and strict rules required students to rise early, dress in naval-style uniforms, and salute instructors. It was a far cry from his hometown life, where friends called him “Party Boy”—a fitting nickname for the son of a regional brewery owner who’d begun working in the family’s warehouse stacking cases of beer a few summers back.
When his parents visited a month into the term, Dick begged them to take him home so he could learn about the family business. They refused. With the industry struggling, they hoped their son’s new surroundings would inspire him to pursue a more promising future away from beer.
Dick had other plans. After convincing a maintenance man to give him civilian clothes, he climbed a tree and jumped over a wall to escape the forty-acre campus. He hopped on a bus to Philadelphia before hitchhiking home, unable to stay away from the brewery he loved. His return home with little more than the clothes on his back would foreshadow the resourceful way he would ultimately go on to turn the struggling family enterprise into one of the country’s most successful beer producers, becoming a billionaire at the time his chief rival squandered what could’ve turned into a nine-billion-dollar company.
Started in 1829 as the Eagle Brewery by his German ancestors, the business had outlasted scores of other brewers by the time Dick took over for his ailing father in 1985. The three major players—Anheuser-Busch, Miller, and Stroh—controlled 70 percent of the national beer market. Dick’s brewery put out a modest 137,000 barrels annually, a drop in the bucket of the close to 200 million barrels produced nationwide. Faced with competition from these mega-companies, smaller producers typically took one of two paths. Some gave up as independents and sold themselves to competitors. Others tried to grow rapidly through acquisitions.
Dick rejected both options. He wouldn’t sell, and he wouldn’t buy. Instead, he’d find better ways to work with what he had to build a prosperous business he’d enjoy running.
Although big marketing dollars typically drove beer sales, Dick found ways to get more out of his modest advertising budget. He built awareness by tapping into his company’s rich but underutilized history. America’s oldest brewery had a type of appeal that separated its products from the three major producers.
Instead of entering as many markets as possible, Dick limited sales to only a handful of regions, creating a sense of scarcity that drove more demand. A cult-like group of fans would cross state borders to buy the hard-to-get beer, lending a mystique to the brand. Several enthusiasts became the beer’s best, and free, advertisers, and even started campaigns to appeal to the company to come to their part of the country. As his business grew, Dick purchased used tanks, bottlers, and labelers—giving them a second life.
By 1996, Dick’s efforts to get the most out of his 150-plus-year-old factory were so successful that the five hundred thousand barrels the company brewed finally maxed out the facility, which had been built to produce only about half as much.
Before investing in another plant, he consulted with his most important partners—his four daughters. With only three percent of family businesses making it to the fourth generation or beyond, he wanted to gauge their passion for becoming sixth generation owners. Only after they enthusiastically expressed interest did Dick see a purpose in continuing to grow the business.
Dick’s company, D. G. Yuengling & Son, grew into America’s largest domestically owned beer producer. But that was never his goal. “We were not in any race to be the largest domestically-owned brewer,” he reflects. “Our game is longevity . . . My daughters . . . are in the business now and we want their kids to be able to run it some day. That’s what’s satisfying to us.”
Forbes estimates the blue jeans- and sneaker-wearing leader of the beer giant has a net worth of close to $2 billion. Even with all of his wealth, he still drives a modest car and regularly turns off lights left on at the office. “They say I’m cheap,” he told me, “but I’m economical.”
His motto—to work with what he has and make the most out of it—helped him achieve the elusive goal of creating a thriving and sustainable business he enjoys running alongside his children.
What made Dick so successful and satisfied when so many other breweries went bust, running themselves and their companies into the ground?
As a social scientist and Rice University professor, I’ve spent over a decade studying what makes organizations more prosperous and the people who work inside them better off. I’ve researched, consulted with, or worked at organizations in industries as diverse as technology, manufacturing, banking, retail, energy, health care, and nonprofits, spending time with top executives at Fortune 500 companies, entrepreneurs launching their businesses, front-line employees trying to make a difference, and everyone in between.
What I’ve found in my research, and what a growing body of scientific evidence supports, is that how we think about and use resources has a tremendous influence on professional success, personal satisfaction, and organizational performance. We routinely overestimate the importance of acquiring resources but even more significantly underestimate our ability to make more out of those we have.
Whether adapting to major changes, going about everyday routines, or trying to carve out meaningful careers and lives, my research explains how people and organizations can expand their resources to achieve great things and feel fulfilled—to stretch. Stretching is a learned set of attitudes and skills that comes from a simple but powerful shift from wanting more resources to embracing and acting on the possibilities of our resources already in hand.
Scott Sonenshein is the Henry Gardiner Symonds Professor of Management at Jones Graduate School of Business at Rice University.
Advertising reaches potential investors, who tend to invest in what they know.
Based on research by Gustavo Grullon, George Kanatas and James P. Weston
Investors Buy What They Know
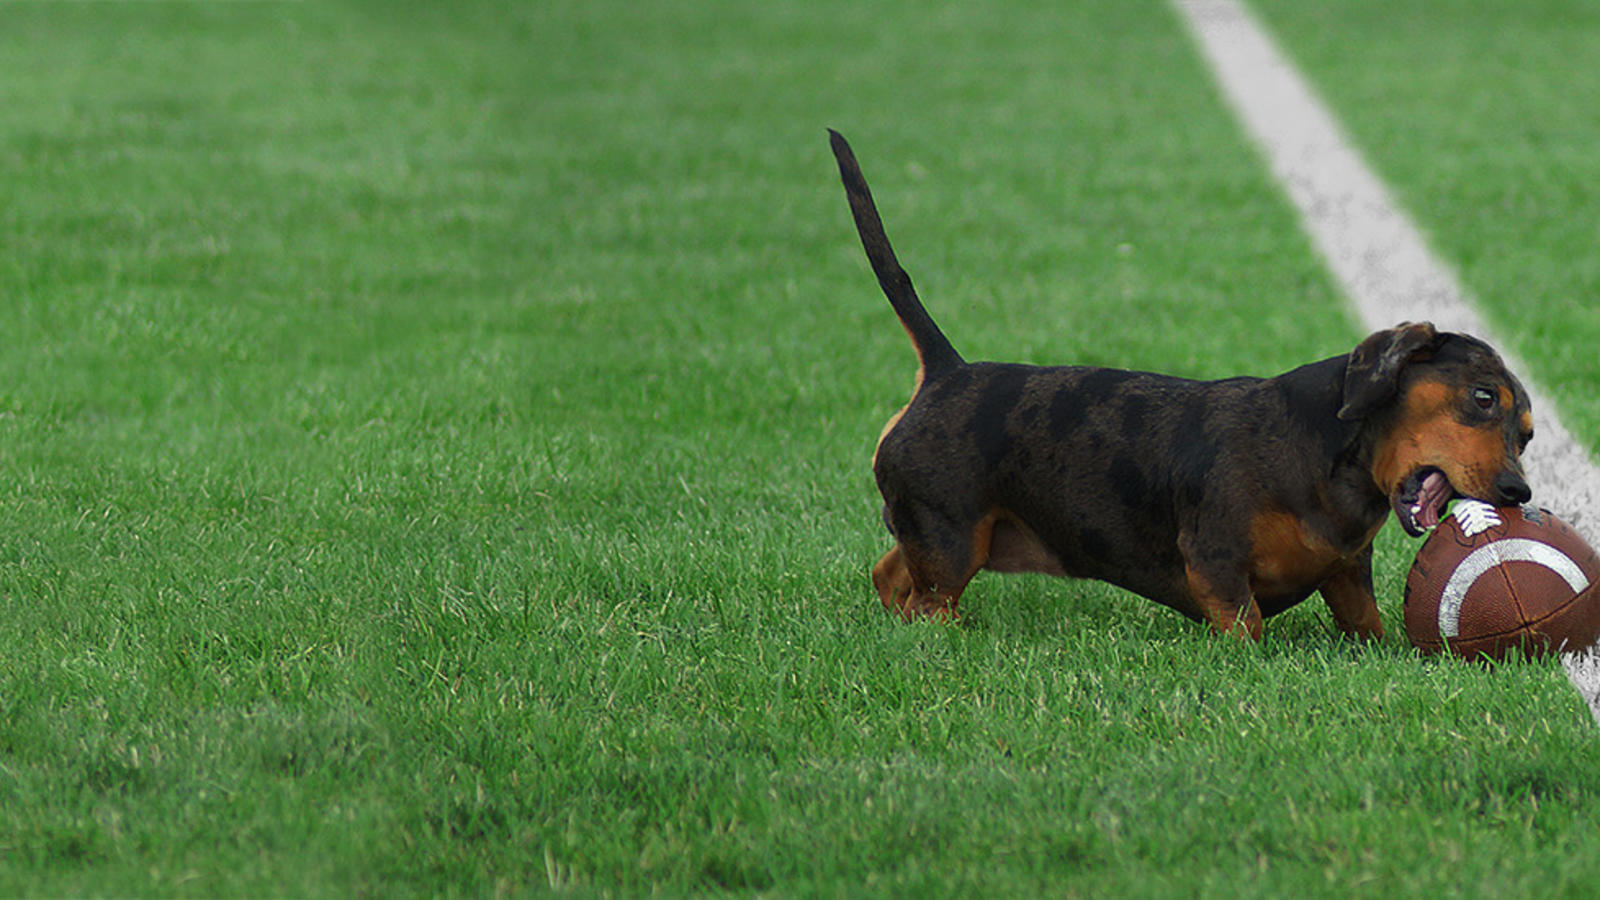
In the 2016 Super Bowl, 30 seconds of commercial airtime cost up to $5 million. How did the H. J. Heinz Company spend their expensive time?
With a pack of dachshunds dressed like hot dogs racing in slow motion toward owners dressed like ketchup bottles.
The Heinz “Weiner Stampede” was a viewer favorite, and a fine investment it was. Absurd, yes, but it not only prompted shoppers to remember Heinz at the store – it probably nudged Wall Street investors to buy shares.
Product sales, a team of business school researchers have found, are just one way to measure marketing success.
While most people think of brand recognition simply as a way to reach consumers, there’s another important constituency that responds to familiar names and products: investors.
A study coauthored by finance professors Gustavo Grullon and James P. Weston, and Emeritus Professor George Kanatas, shows that when firms spend more on advertising, they attract significantly more investors. This so-called “home bias” sways individual investors more than it moves institutional investors. But its effect on both is the same: A disproportionate number of investors are drawn to a stock based on familiarity rather than more fundamental information.
“People buy on impulse and on recognition,” Weston explained to Fortune. “With more and more online trading taking place, companies that spend money on big advertising campaigns see this additional benefit from their advertising investment.”
The Rice team’s research was based on a sample of 5,776 firms. Their findings showed that on average a 10 percent increase in advertising expenditures increased the number of independent shareholders by 2.7 percent. Institutional shareholders climbed 0.5 percent.
With more investors, a firm’s shareholder base and liquidity grow. And since a firm’s visibility may increase the breadth of ownership and improve liquidity, it is possible that brand familiarity can also increase a firm’s overall value.
This research has important implications for firms considering the economics of advertising. Old-fashioned marketing — the kind that emphasizes pets, funny slogans, familiar images — influences more than customers. It persuades investors.
Just follow the dachshunds. As the weenie dogs barrel their way across the Heinz commercial, a voice-over tells viewers, "It’s hard to resist great taste.” Whether investing in ketchup or stock shares, buyers agree.
George Kanatas is a Jesse H. Jones Professor Emeritus of Finance
Gustavo Grullon is a Jesse H. Jones Professor of Finance at the Jones Graduate School of Business at Rice University
James P. Weston is a Harmon Whittington professor of finance at the Jones Graduate School of Business at Rice University
To learn more, please see: Grullon, G., Kanatas, G., & Weston, J. P. (2004). Advertising, breadth of ownership, and liquidity. Review of Financial Studies 17(2), 439–461.
U.S. consumers and businesses are now facing a future of more expensive borrowing.
Veterans thrive in MBA Program at Rice Business.
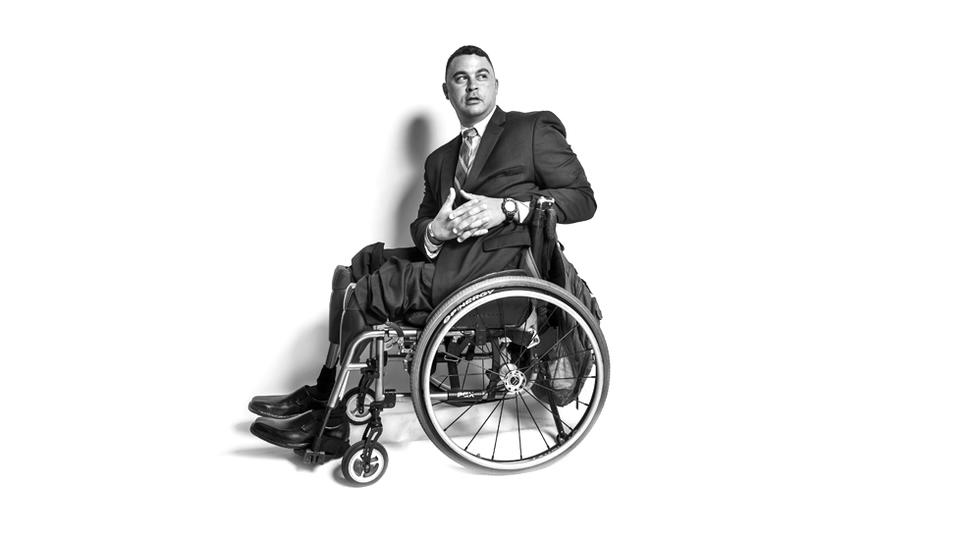
By Michael Hardy
Veterans Thrive In MBA Program At Rice Business
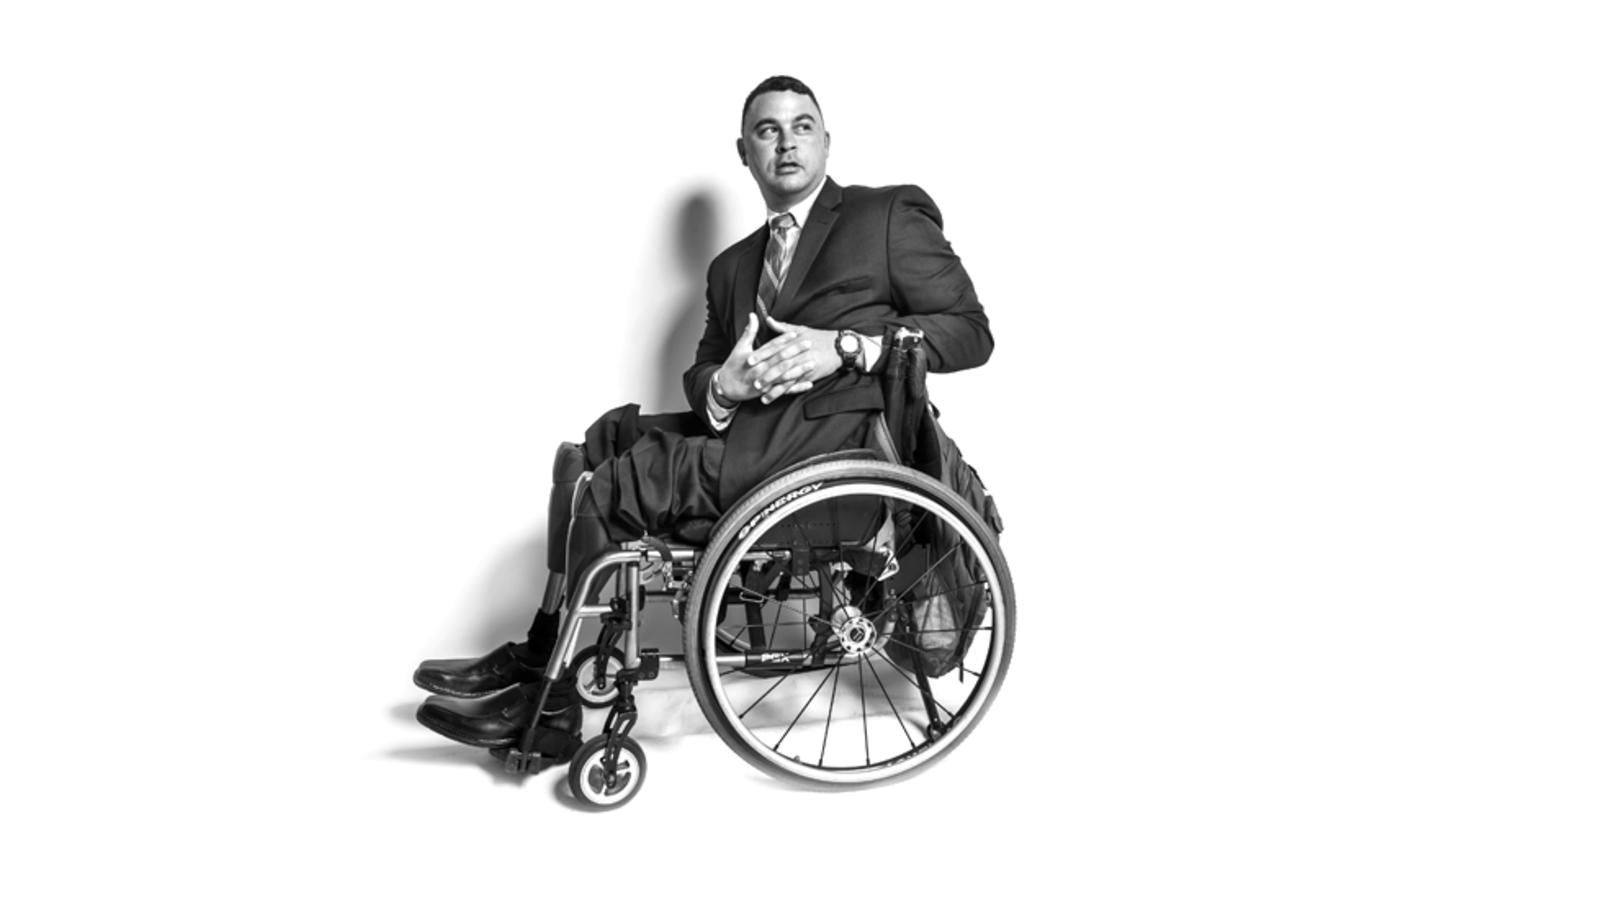
This article by Michael Hardy (Rice ’06) originally appeared in the Winter 2016 issue of Rice Magazine. The photo of Will Lyles is by Tommy LaVergne.
Four days after his 30th birthday in 2010, Maj. William E. Lyles was leading a team of Army Green Berets on a mission to meet with tribal leaders in the village of Garmab, in Afghanistan’s remote, mountainous Urozgan Province, when their Humvees began taking small-arms fire. Lyles directed his driver to take up a position on a hilltop to the north of the village, where he jumped out to assess the situation. He was in the process of radioing back to base to request air support when he stepped on a buried IED (improvised explosive device).
“At first I thought it was a mortar round,” Lyles remembered. “All my teeth were loose. My legs felt heavy, but there was this cloud of dust so I couldn’t see what had happened. I was trying to get up and get back in the fight, and I just couldn’t.”
When the dust finally cleared, Lyles saw that his right leg had been severed above the knee and his left leg was gone below the shin. “I didn’t think I was going to make it,” he said. “I tried to take deep breaths, because if you freak out you go into shock, and I knew I wouldn’t have a chance.”
Today, after four years of grueling rehab at the Brooke Army Medical Center in San Antonio, Lyles is a first-year MBA student at the Jones Graduate School of Business. He’s adjusted to life without his legs — he uses a wheelchair and two prosthetic legs to get around now — but the adjustment to civilian life, which included the breakup of his marriage, has been rocky at times. “I miss the Army more than anything,” he said. “I wish I was still able to do what I did, but this is good, too. I’m going to get a chance to lead again, in a different capacity.”
Lyles is part of a large and growing veteran presence at the Jones School — 10 percent of students enrolled across the school’s three MBA programs (full time, professional and executive) have served in the armed forces. In 2009, Rice was one of the first schools to join the Yellow Ribbon Program, which provides federal matching funds to help veterans attend private schools where the post-9/11 GI Bill often doesn’t cover the full cost of tuition.
Former Navy SEAL Jimmy Battista ’13 enrolled in the Jones School in 2011 after a decade in the military. Rice (and Houston) offered ready access to the world’s oil and gas economy, which is where he hoped his post-military career would lead him. “I realized that oil and gas companies operate in similar places to where I was operating — Iraq, Yemen, hard places to operate,” Battista said. Along with his fellow military classmates, Battista founded the Veterans in Business Association (VIBA) to provide mentoring for students making the transition from the military to academia.
Support soon coalesced around the idea to create an annual scholarship to cover tuition, fees and living expenses for one veteran to earn a graduate business degree. Jones Graduate School of Business Dean Bill Glick, along with Rice trustees and members of Jones’ leadership team inaugurated the scholarship in 2012. (Lyles is this year’s recipient.)
“Here, veterans get a two-year window after they come out of the military to figure out what they want to do,” Glick said. “And in the process they figure out which parts of their military leadership training actually translate into the business world. They come in with advanced leadership skills in some dimensions, and we give them opportunities to grow and develop. And vets are very good at doing that. They’ve got a great sense of mission.”
Admission officers at the Jones School take into consideration the specific challenges facing veterans — “You can’t take a Princeton Review GMAT course in Kandahar,” one veteran said.
Annie Hunnel, a former associate director of recruiting and admissions at the Jones School, travels the country to meet potential students at service academy career days and veteran job fairs. “When a veteran transitions out of the military, they don’t necessarily understand what their options are,” Hunnel said. “It’s hard to understand how to put that experience in a résumé, how to make themselves attractive to an employer.”
One of VIBA’s earliest supporters was Rice trustee Doug Foshee, the former CEO of the El Paso Corporation and a 1992 Jones School alumnus. “I was aware that many of my fellow Houston CEOs were flying to Boston every year to recruit military veteran MBAs from the Rice University of the North, otherwise known as Harvard,” he said. “That didn’t make a lot of sense to me — why couldn’t we grow our own?”
In a very short period, Foshee said, the Jones School has become known as one of the most veteran-friendly business schools in the country. In fiscal year 2014, it awarded more than $1 million to the Military Scholars Program finalists and $1.7 million overall to veterans in the business school.
That reputation is what helped attract Steve Panagiotou, who, like Lyles, is a former Green Beret. After 10 years in the Army, Panagiotou was trying to decide how to jump-start his career when a friend told him about the Jones School.
“Rice valued my background in the military, and when I came down and got to meet some of the supporters, that clinched it,” he said. “The support was almost overwhelming from the alumni who have been successful in their careers. At that point it was a no-brainer for me.”
As the current president of VIBA, Panagiotou has played a role in sponsoring public events like the Rice Veteran's Leadership Series, which has featured marquee speakers such as Tom Ridge, the first secretary of the Department of Homeland Security, and Pete Dawkins, a legendary American business leader, distinguished veteran, Rhodes Scholar and Heisman Trophy winner.
The group scored a coup in 2013 when it brought to campus six major American authors (four of whom were veterans) to help raise the profile of the Jones School and its veteran-friendly programs. Organized by then-MBA student and VIBA president Mike Freedman ’14, the event featured authors David Abrams (“Fobbit”), Lea Carpenter (“Eleven Days”), Ben Fountain (“Billy Lynn’s Long Halftime Walk”), Bruce Jay Friedman (“Stern”), Karl Marlantes (“Matterhorn: A Novel of the Vietnam War”) and Rice alumnus Bill Broyles Jr. ’66, who served in Vietnam before returning to Texas to co-found Texas Monthly and go on to a distinguished career in screenwriting. In 1983, Broyles was one of the first American veterans to return to Vietnam, this time to “meet my enemy in peace,” as he wrote in the resulting chronicle, “Brothers in Arms.”
The event drew a full house and resulted in substantial discussion about the poignancy and pathos of war, the ethics of reportage and the impact of humor and absurdity in such chronicles. “To be with writers like Karl Marlantes, Bruce Jay Friedman and Ben Fountain was a rare opportunity,” Broyles said. “The discussion was deep and raw and honest, and the Rice vets were incredibly inspiring.”
Though they weren’t part of the program last fall, Broyles, Fountain and Marlantes returned to campus to attend another VIBA-sponsored writer- and vet-friendly event marking the 50th anniversary of the Vietnam War. At that event, Broyles noted “the same spirit of support and comradeship.”
“A small group of dedicated men and women have been fighting a lonely war for almost 15 years now,” he said, “and I’m so proud of Rice for honoring and supporting these veterans and of the veterans for making Rice an even better place.”
Like Panagiotou, Lyles decided to come to Rice after sitting in on classes and meeting veterans already enrolled in the program; being awarded a full scholarship sealed the deal. Despite having lost both his legs in Afghanistan, the recently remarried father of four said he feels blessed to be given a fresh start. “I consider myself probably the luckiest person in the world. I hit the lottery, but instead of money, it’s a second chance at life. And I want to make the most of that second chance.”
How well-placed reminders help consumers build sustainable habits.
“Social mandates” can make a company’s response seem more genuine.
Many tests, big conclusions: What could possibly go wrong?
Based on research by David Lane
Many Tests, Big Conclusions: What Could Possibly Go Wrong?
Most people know at least a little about the signs of the zodiac, and the supposed characteristics of those born under them. Aries are brave; Cancers tenacious; Scorpios resourceful. But did you know that Sagittarians are prone to funny-bone fractures? Or that Leos tend to be plagued by stomachaches?
It all sounds like nonsense, you say — especially the part about diseases and injuries being linked to astrological signs. But according to David Lane, an associate professor of statistics and management at Rice, those indeed were the findings of a 2006 study that classified patients according to their signs, and then went looking for any differences in incidence of particular ailments.
Don’t get Lane wrong, though. He in no way defends the notion that diseases and star signs are linked. Neither did the authors of the original study, which was designed as a lesson in the perils of shoddy science. Instead, in an article critiquing the careless use of statistics, Lane warns that research that makes too many statistical comparisons boosts the chances of false conclusions.
In other words, if scholars conducting a study focus on too many subgroups — Geminis and Capricorns, say — rather than on the big picture, they're likely to get inaccurate, even nonsensical, findings.
These studies also pose a special hazard for science reporters. Lacking background in statistics and numeracy, such journalists can easily misunderstand studies that are statistically complex.
Lane uses the New York Times blog of Steve Lohr to illustrate his point. In 2010, the National Bureau of Economic Research published a report on the effectiveness of online education. Lohr quoted the report's authors, who wrote, “A rush to online education may come at more of a cost than educators may expect,” and generally conveyed skepticism about the “rush” to online college learning, especially regarding “certain groups” that “did notably worse online.”
Hispanics who studied online, these authors contended, scored a full letter grade lower than Hispanics who attended a live lecture. Males and low achievers each lost half a letter grade.
To the casual reader, this looked like bad news about online education overall. Readers who weren’t statistically savvy also might have concluded that Latino online learners fare especially badly, and that online classes don’t work as well as in-person teaching for anyone. But none of that was actually supported by the report’s findings.
According to Lane, the blog failed to convey a rather important fact: there is “no credible evidence" for the notion that live lectures have any better outcomes than online ones.
Even more misleadingly, the Times blog didn’t reveal that the sample size for the Hispanics viewing online lectures was only eight people. While the overall group tested was an adequate 312 students, Lohr failed to note the small number of Hispanics who were viewing online lectures.
In other words, the New York Times reported on the performance of Hispanic students in online classes based on a study that included only eight Hispanics in the critical group. “A proper comparison," Lane writes, "would take into consideration the large margin of error that necessarily accompanies the very small sample size used.”
Lane’s article sends up a warning about research findings based on subgroups to the exclusion of the big picture. It’s the scientific equivalent of believing that the cosmos revolves around the Big Dipper.
There’s good reason, in other words, to doubt that Sagittarians have fragile bones. Sound science requires a grasp of statistical complexity – and acknowledgment that the universe holds more than just the stars we can see.
David M. Lane is an associate professor in the departments of psychology, statistics and management at Rice University.
To learn more, please see: Lane, D.M. (2013). The problem of too many statistical tests: Subgroup analyses in a study comparing the effectiveness of online and live lectures. Numeracy, 6(1), Article 7.
How federal monetary policy can influence equity (and inequity) in home buying.